Will a Temporary Loss of Income Impact Your Mortgage Post-COVID-19?

Anita Groves • November 3, 2020

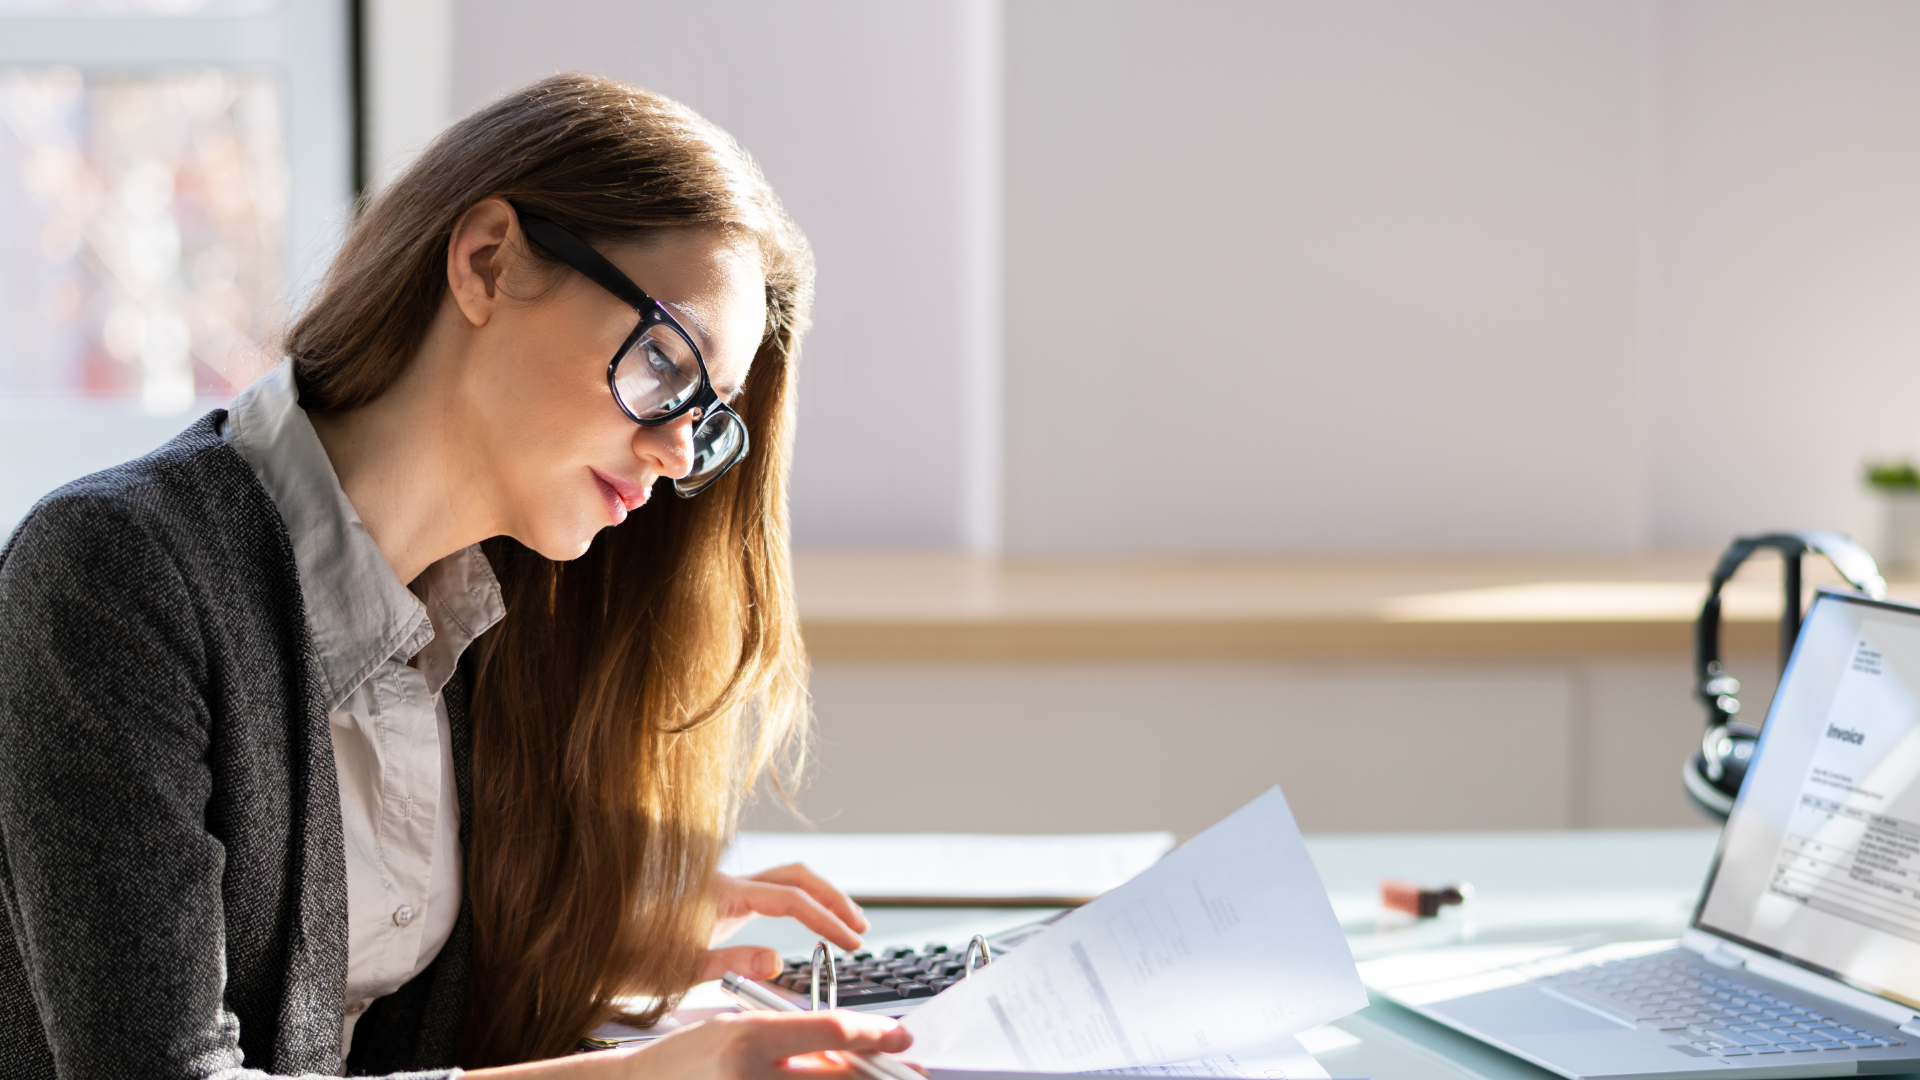
While unemployment peaked over 13% at the onset, it’s hard to quantify just how many Canadians had some form of a reduction in their income over the last year. Especially if you’re self-employed or your income varies year to year because you receive a bonus, pick up shifts, freelance, or you earn income that isn’t guaranteed.

If you earn variable income, and you’ve seen a reduction in income because of the pandemic, this has the potential to impact how much mortgage you qualify for up to the next three years.

Here’s why. For income that isn’t guaranteed, when assessing your mortgage application, most of the time, lenders will look at a 2-year average. So let’s say you’re looking to secure a mortgage now in 2020, the lender will want to see documentation proving what you earned in 2018 and 2019, and they will take a 2-year average.

If your income is lower in 2020 because of the pandemic, once we come to tax time in 2021, your 2-year average will now include that reduction in revenue for the next couple of years, even if you are back to making what you did pre-pandemic. It will be the same case in 2022 (and into 2023), as any lender will want to see your 2-year average between 2020 and 2021. Less income in 2020 could mean qualifying for a lower mortgage amount over the next few years.

The advantage of working with an independent mortgage professional is the ability we have to represent you to several lenders who all offer different products and have different guidelines. So while one lender might be hard and fast on the 2-year average, depending on your industry, another lender might make an exception.

Additionally, depending on where the housing market is at and how much the economy has rebounded in 2021, lenders might consider COVID-19 and be flexible or implement amended guidelines. However, we will have to wait and see on that. But for the most part, if your income is lower because of COVID, it will impact you going forward, feel free to get in touch if you have any questions or hear anything in the news that you’d like clarified.

So what can you do about this today? Well, if you’re currently looking to purchase a property or you have a mortgage that’s almost up for renewal, or if you’d like to refinance before 2021, it’s definitely in your best interest to talk with an independent mortgage professional about all your options as soon as possible.

Alternatively, if you’re not looking to secure a mortgage right now, it’s always a good idea to have a plan in place for when you do. It never hurts to plan ahead, especially when you have time and can make up some of the lost income with additional income in the future.


If you’d like to discuss your financial situation and see exactly how your income impacts your mortgage qualification, please don’t hesitate to contact me anytime, I would love to work through everything with you!


Share
Kevin Roye

PROFESSIONAL MORTGAGE BROKER
CONTACT ME APPLY NOW

Download My Mortgage App HERE

Recent Posts


By Kevin Roye • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Kevin Roye • October 21, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.